EMI Calculator
Find your monthly EMI, total interest and total payment for any loan.
Home • Car • Education • PersonalThis is an estimate using the standard reducing-balance formula. Your bank may charge processing fees or use a slightly different rate.
Taking a loan is a big decision, and the first question most of us ask is simple: how much will I pay every month? Whether it is a home loan, a car loan, an education loan or a personal loan, the EMI decides how comfortable the next few years will feel. This free EMI calculator gives you the answer in a few seconds, along with the total interest you will pay, so you can plan before you sign anything.
We built it to be quick on a phone. There is nothing to download and no sign-up. Move the sliders or type the numbers, and the result updates right away.
How to use the EMI calculator
- Enter the loan amount you want to borrow.
- Enter the yearly interest rate offered by the bank or lender.
- Enter the loan tenure in years.
- Tap Calculate. You will see the monthly EMI, the total interest and the total amount you will pay back, with a simple chart of principal vs interest.
How EMI is calculated
Banks in India use the reducing-balance method. The formula is:
EMI = P × r × (1 + r)n ÷ [(1 + r)n − 1]
- P = loan amount
- r = monthly interest rate (yearly rate ÷ 12 ÷ 100)
- n = number of monthly instalments (years × 12)
In the early months a large part of each EMI goes towards interest. As the loan balance falls, more of the EMI goes towards the principal.
A worked example
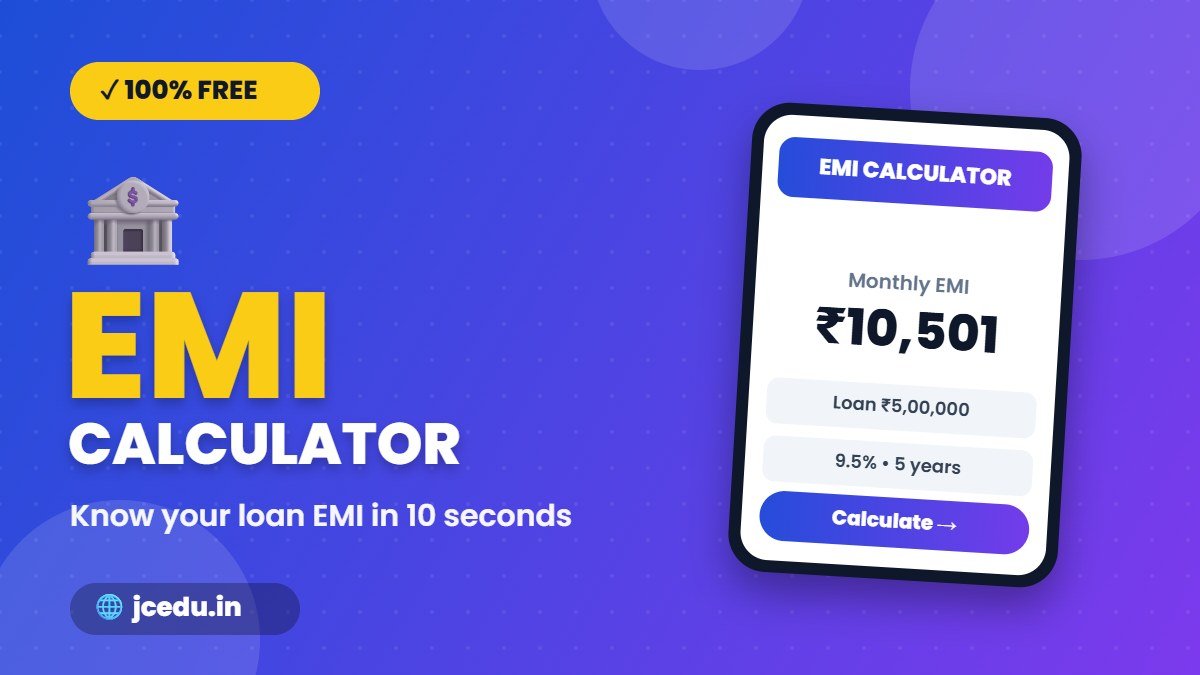
Say you take a personal loan of ₹5,00,000 at 9.5% a year for 5 years. Your EMI comes to about ₹10,501 a month. Over 60 months you pay about ₹6,30,056, which means roughly ₹1,30,056 goes to interest.
Tenure makes a big difference. On a home loan of ₹30,00,000 at 8.5%, the EMI is about ₹29,542 for 15 years and about ₹26,035 for 20 years. The 20-year EMI is lower, but the total interest rises from about ₹23,17,594 to about ₹32,48,327. Try both in the calculator before you choose.
Tips before you take a loan
- Keep all your EMIs together under about 40–50% of your monthly take-home pay, so you still have money for daily needs and savings.
- Compare the interest rate and the processing fee of at least two or three lenders.
- If you get a bonus or extra income, a small part-prepayment can cut your interest a lot, especially in the early years of a loan.
- Read the loan agreement for prepayment charges, late fees and insurance that may be added to the loan.
Frequently asked questions
Is this EMI the same as my bank EMI?
It is a close estimate for a fixed-rate loan. Your bank may add processing fees or insurance, or round the numbers differently, so the EMI in your loan agreement can differ slightly.
Can I use it for home, car, education and personal loans?
Yes. The formula is the same for all fixed-rate loans. For floating-rate home loans, the EMI or tenure changes when the bank changes its rate.
How can I reduce my EMI?
Make a bigger down payment, choose a longer tenure, or negotiate a lower rate. Remember that a longer tenure lowers the EMI but increases the total interest.
Is my data saved?
No. The calculation runs in your browser and we do not ask for your name, phone number or any loan details.
Planning to invest instead of borrowing? Try our SIP calculator or FD calculator.